A payment setup should make it easier to get paid, not leave you guessing about fees, checkout steps, or who handles a problem. Kris Chislett has worked with businesses since 2010 and offers Merchant Processing guidance for companies in Oldsmar FL evaluating how to accept payments. The first step is to clarify how customers pay today, where transactions happen, and what is not working. That conversation helps determine whether the requested support fits the business need before any next step is proposed.
What does the service address? Merchant processing generally involves the systems and provider arrangements that allow a business to accept card or other electronic payments and receive funds. The right setup depends on the business model: a professional service may need a straightforward way to collect invoices, while an ecommerce brand may need payment steps that work smoothly within its online checkout. These are examples, not claims about past clients. Specific provider selection, account approval, pricing, and technical implementation depend on the requirements established during the discussion.
Could this be a fit for your company? The service is relevant to small and medium-sized businesses, professional services, ecommerce brands, and service-based companies that want to assess payment acceptance or improve how it supports their customer journey. It is not a bank, payment processor, or promise of account approval. If you need a provider to underwrite an account, set transaction rates, or resolve a processor-side dispute, those decisions remain with the provider. Kris Chislett can help define the business questions and marketing context to bring into that evaluation. For merchant processing oldsmar fl, Kris Chislett helps businesses choose a payment setup with clear fees, straightforward checkout, and support when issues arise. With experience serving businesses since 2010, he can help you find a solution that fits your needs.
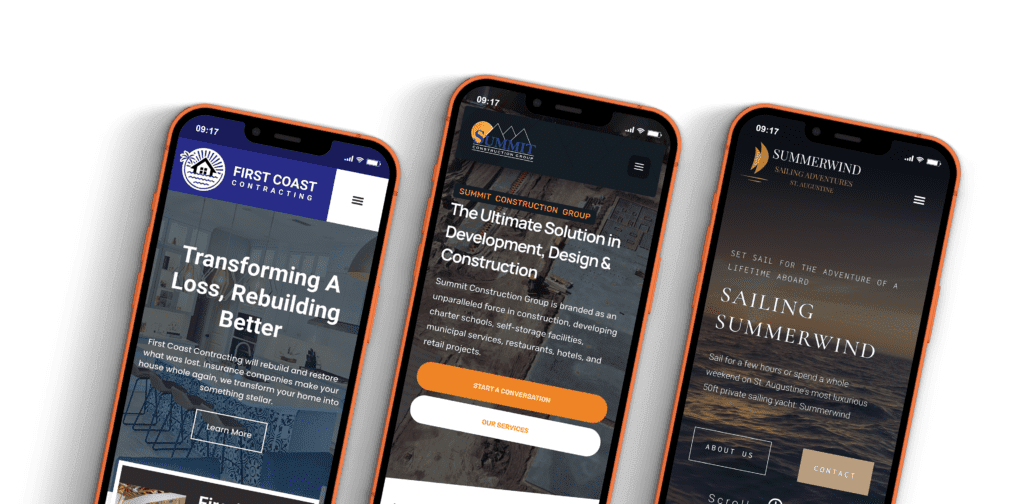
Creating an industry-leading website is about much more than “making it look pretty.” Before we start any website build, we always take a look at what your competitors are doing, establish your audience, and define your goals. This makes sure we deliver a site that not only speaks directly to your customer but makes you the obvious choice over the competition.
We’re on a mission to craft dynamic web solutions that blaze a clear trail, guiding your audience straight to your call to action. It’s all tailored just for you – captivating content, sleek design, and applications like custom databases or customer web portals. Throughout this dynamic journey, you’ll be at the forefront, ensuring we align with your business goals.
A great website is never finished, and we make sure we always build in a way that allows you to update your own content (with free training provided.) But you don’t have to do this alone! Our team of experts will help you get the most out of your online presence and make ourselves available to discuss further marketing efforts.
Are customers unsure how to pay, or does your team spend time explaining a process that should be clear? Confusing checkout steps, disconnected payment touchpoints, and uncertainty about transaction costs can make a business’s payment experience harder to manage. A review can help identify what needs clarification and which questions should go to a processor, website provider, or marketing partner. It does not establish that a particular provider is at fault or guarantee a change in transaction outcomes.
A review may be timely after a website change, a shift from in-person to online sales, the addition of a new service, or repeated customer questions about payment. These situations can reveal mismatches between how a business sells and how it collects payment. Before changing providers, compare the current agreement, fee structure, supported payment methods, settlement details, and any contract terms with the actual business need. Avoid sharing full card numbers or security codes during an initial discussion.
What should improve? Set practical goals such as making payment instructions easier to find, reducing unnecessary checkout steps, or giving staff a clearer process for directing account questions. Those goals are different from guaranteed increases in sales or approval rates. Clicks, checkout starts, and completed transactions each measure different behavior; none alone proves that a payment change caused business growth. A useful evaluation connects the customer experience to the business’s own records and acknowledges what the available data cannot show.
What happens first? During the initial conversation, explain your business model, current payment methods, customer concerns, and the change you are considering. Share only information needed to describe the issue; do not send sensitive payment credentials. Kris Chislett typically responds within a few hours during business days, with availability Monday to Friday. That response expectation applies to communication, not to processor approval, account activation, or a guaranteed project completion date.
Next, the requirements and existing customer journey can be mapped: where a customer chooses a payment method, what information they see, and where questions or friction arise. The appropriate review may involve website content, checkout presentation, or the questions to take to a payment provider. Any recommendation depends on the agreed scope and access available. The business remains responsible for provider contracts, account applications, transaction records, and decisions that only the provider can make.
After the review, the next step is to agree on a defined scope, responsibilities, and any needed coordination before work begins. Timing depends on the complexity of the request, the platforms involved, and how quickly required information or access is available. Provider onboarding or technical changes may follow a separate schedule controlled by third parties. No fixed turnaround should be assumed until the specific work is understood, and a proposed plan should distinguish marketing or website tasks from processor-side actions.
How is the work grounded? Kris Chislett was founded in 2010, and the supplied credentials include Google Partner, Meta Business Partner, HubSpot Certified, and SEMrush Certified. These credentials relate to digital marketing platforms and capabilities; they are not payment-processing licenses, bank affiliations, or proof of processor approval. That distinction matters when evaluating who is responsible for payment account terms, transaction security, and funds movement.
The working approach is collaborative: clarify the business objective, review the customer-facing payment experience, and agree on the next action with the client. This helps keep recommendations connected to the actual sales path instead of treating a processor change as a guaranteed fix. If measurement is part of the agreed work, the indicators should match the goal, such as whether payment instructions are visible or whether customers complete a defined checkout step. Attribution can be limited by platform reporting, consent choices, and activity outside the measured journey.
Cost depends on the requested work, the platforms involved, and whether the need is strategic guidance, website-related support, or coordination around a broader marketing task. Processor rates, account fees, and contract charges are set by the relevant provider and are separate from Kris Chislett’s service fees. Ask for the proposed scope and applicable costs before approving work. There is no supplied basis for stating a standard price, warranty, guaranteed outcome, or refund policy, so those terms should be confirmed in writing for any specific engagement.
A payment provider handles its own account approval, transaction terms, and processing services, while marketing or website support can help clarify the customer-facing payment journey and business requirements. Compare the provider’s fees, contract terms, supported methods, and service responsibilities separately from any consulting or digital work. Ask who owns each task before making a change.
Avoid choosing on a headline rate alone or overlooking contract terms, settlement timing, supported payment methods, and integration needs. Confirm how the change affects your website or point-of-sale workflow, and keep records of the current setup. Never share card details or security credentials in an ordinary marketing inquiry.
The cost depends on the agreed work, platforms involved, and whether the request is guidance, website-related support, or coordination. Processor fees and account charges are separate and are set by the provider. Request a written scope and cost details before authorizing work.
Prepare a short description of your business, how customers pay, the issue you want to solve, and the payment or website platform involved. Do not include card numbers, security codes, passwords, or other sensitive credentials. Kris Chislett typically responds within a few hours during business days.
Every business should have a strong online presence. If you don’t, you’re leaving money on the table and sabotaging your own success. That’s where we come in. Let us help. In the ever-changing digital landscape, our coordinated marketing solutions help businesses navigate through the chaos, position themselves for success, and emerge as industry leaders.